Is a comprehensive "interest rate cut" coming?
Director Wen/Tan
On May 11th, three heavyweight news came from the market one after another, which was mixed.
First, the data released by the National Bureau of Statistics,In April, CPI increased by 0.1% year-on-year and decreased by 0.1% quarter-on-quarter.
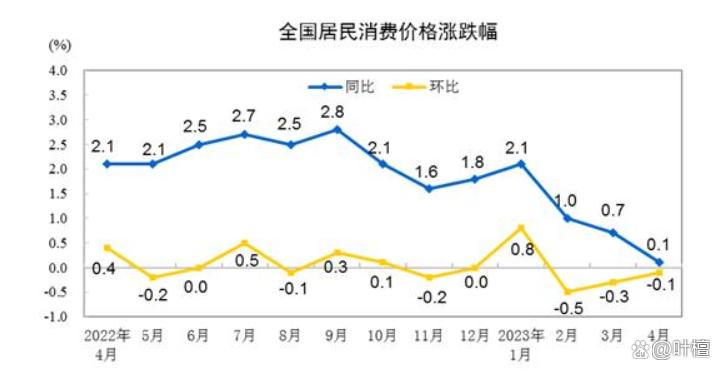
Source: National Bureau of Statistics
In 2023, CPI has dropped three times in a row, and the controversy about whether there is deflation has come again.
After that, more heavy news came soon.The deposit interest rate has come down.
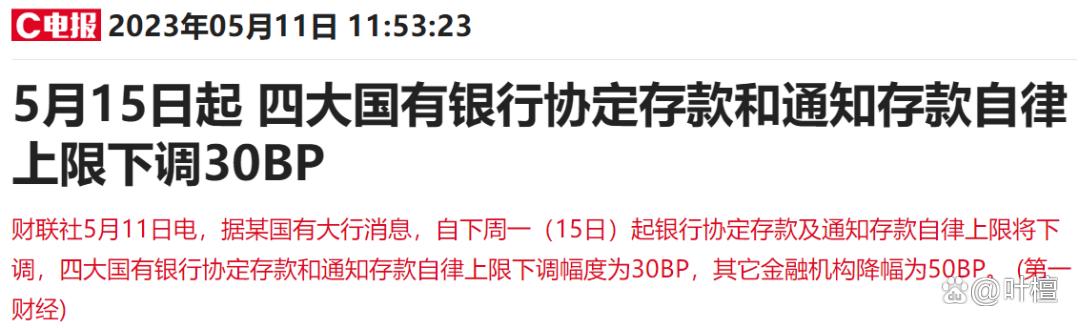
According to reports, the First Financial Reporter learned from a large state-owned bank that from next Monday (15th), the self-regulatory ceiling of agreed deposits and call deposits of banks will be lowered by 30BP, while that of other financial institutions will be lowered by 50BP.
At night,Yang Ma’s April social integration data also came: an increase of 1.22 trillion,It is 272.9 billion yuan more than the same period of last year, but it is far from the market expectation of 2 trillion yuan.
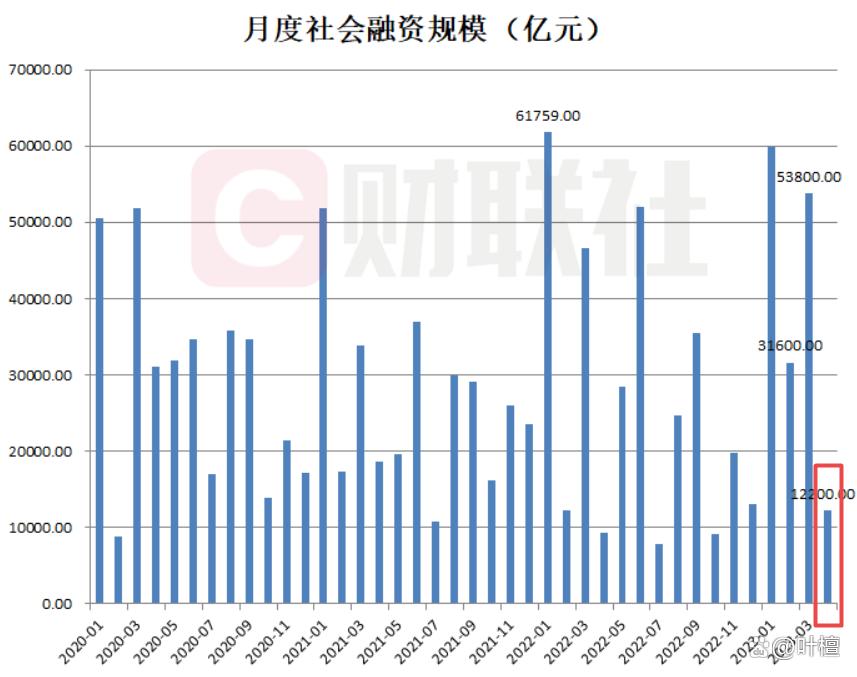
To put it simply, the big goal of stimulating economic recovery is imminent, but the results reflected by the data are still under great pressure, so it is bound to play some important cards.
A new wave of interest rate cuts on deposits and even more stimulus measures are already certain.
Let’s share a report made by the media first.
When I came back from the small holiday in May, someone saw the news that the bank lowered the deposit interest rate and could not help but sigh:
Interest is getting lower and lower, but prices are not getting lower. It’s really too difficult.
Driven by this doubt, a brand-new group was born:"deposit special forces".
In order to get higher interest, the "tourist special forces" and "deposit special forces" who burst into flames during the May 1 ST bid did not hesitate to take the high-speed train across the city to deposit money, just for the interest rate difference of a few tenths.
Such a phenomenon may be only a small number of people, but it is enough to show what kind of mentality ordinary people have about deposit interest rates now.
I don’t listen to consumption, and I just want to save money.
This situation has been talked about since last year, but it has not been effectively improved.
Therefore, from this perspective, the current weakening of CPI this year is also a manifestation of the long-standing existence of this sentiment.
As for deflation, we have always said that there is no need to worry about it, and there is really nothing to say about it.
The economic cycle is always ups and downs, inflation and deflation are always cyclical, and it is difficult for human beings to change the general trend of the economic cycle. The key question is whether it can be controlled, so as not to appear "malignant" phenomenon.
And the attitude of our spokesperson for the National Bureau of Statistics is also very clear."There is no deflation in China’s economy at present, and there will be no deflation in the next stage."
Let’s savor it.
The good news is that the survey report on urban depositors in the first quarter released by Yang Ma this year shows that residents’ willingness to save has finally stopped hitting a record high and started to pick up.
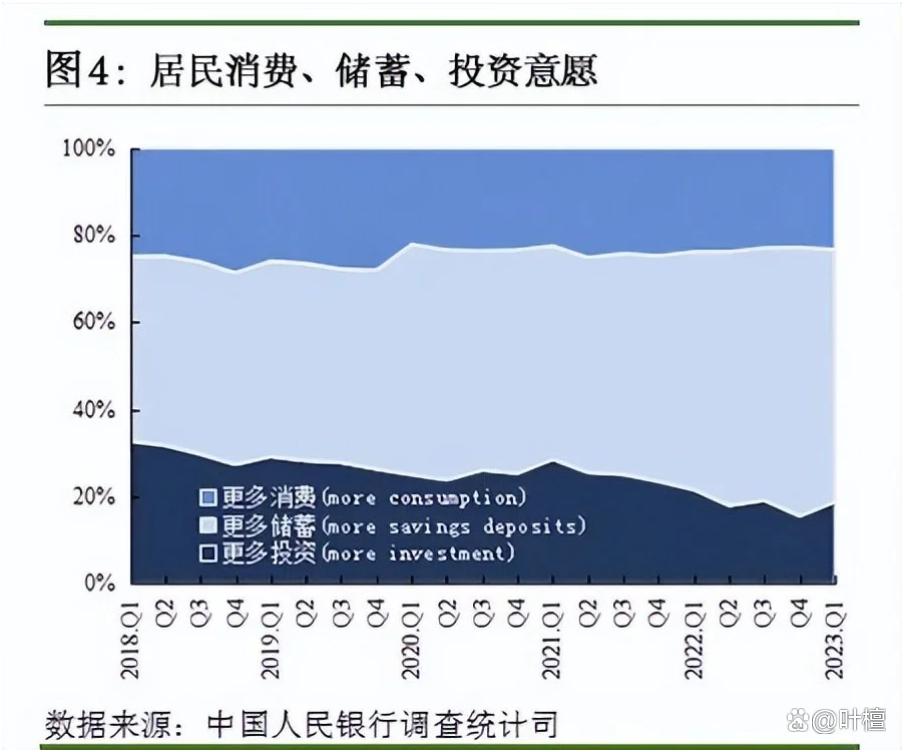
The above figure shows that residents who tend to "spend more" account for 23.2%, an increase of 0.5 percentage points over the previous quarter; Residents who tend to "save more" account for 58.0%, a decrease of 3.8 percentage points over the previous quarter; Residents inclined to "invest more" accounted for 18.8%, an increase of 3.3 percentage points over the previous quarter.
Rome was not built in a day.
Similarly, if we want to reverse this emotional problem, we also need continuous policy stimulus to heat up the consumer market.
As a result, the deposit interest rate has been going down continuously recently.
Recently, A-share banking stocks once became the strongest sector, and brokers and insurance companies, both of which are "golden three fatnesses", have also gained a lot of attention, which may also reflect the market’s strong expectation of continuous interest rate cuts on deposits to some extent.
In fact, we have been seeing intermittently this year, and some banks will report that the deposit interest rate will be lowered from time to time.
The three banks mentioned in the last paragraph (Bohai Bank, Zheshang Bank and hengfeng bank) lowered their deposit interest rates recently.
Most importantly,The deposit interest rates of these banks have all been lowered to below 3%, which may mean that the era of deposit interest rates farewell to 3 is coming.
This time, the upper limit of interest rates for agreed deposits and notice deposits mentioned at the beginning was lowered, which was less concerned by the market before.
Notice deposit is a kind of demand deposit, and the interest rate is higher than the demand deposit. At present, it is mainly divided into two periods: one day and seven days. Agreement deposit is a kind of deposit for enterprises and institutions, and the interest rate is also higher than the demand.
If the interest rate is higher than the average variety, it will naturally lead to some profit-seeking funds "bonus hunter".
This policy is precisely to limit this "bonus hunter" behavior and reduce the amount of "wool" by cutting interest rates in disguise.
For banks, this is definitely a good thing. After all, more deposits mean more costs. Unfortunately, the A-share banking stocks may have overdrawn this good news early.
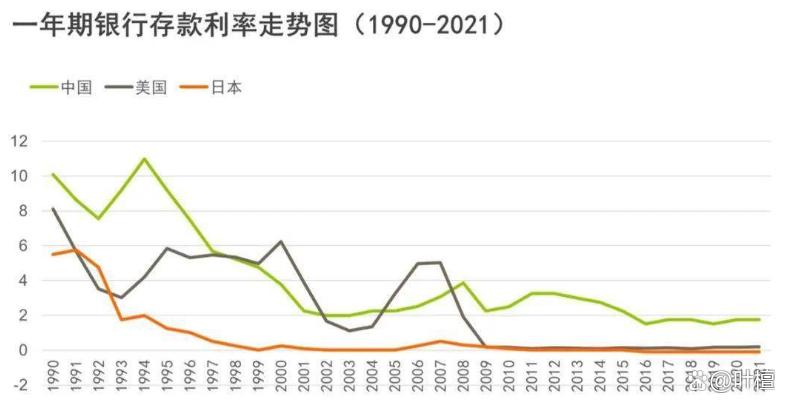
Of course, from a broader perspective, it is nothing new that the deposit interest rate in China continues to fall.
Source: Network
Compared with the long-term interest rate trends in the United States and Japan, China’s interest rate actually has some room for downward adjustment, and this trend cannot be changed.
Entering the era of registration system, China’s capital market continues to develop in the path of overseas mature markets, and the importance of asset allocation will become more and more obvious.
Therefore, for friends who are still thinking about how to save more interest, let’s give up this road. It is a matter of time before you learn to allocate assets and master certain financial management knowledge and skills.
Finally, after we simply sorted out the latest data, a puzzling problem suddenly emerged.
According to the data of the central bank, M2 increased by 12.4% year-on-year, and the growth rate slowed slightly by 0.3% compared with the end of last month.
Most notably, RMB deposits decreased by 460.9 billion yuan in April, of which household deposits decreased by 1.2 trillion yuan.
So that means,The money supply has hardly changed, and residents’ deposits have finally decreased significantly. There should be a large amount of living money coming out and starting to consume.
However, we also know that the CPI growth rate in April was only 0.1%, which is still in decline. It seems that there is no new consumption increase.
Then the question comes:Where the hell is the money? ? ?
Some people say that it may be used to repay the loan in advance. Some people say that it is taken out in advance to prepare for May Day consumption.
As for the truth, we can’t draw a conclusion for the time being. We may have to look at the official data in May to get a general idea.
But in any case, at least the people really began to withdraw money, and the policy effect really began to appear.
The process of reversing confidence is bound to be bumpy and slow, and we cannot expect the economy to improve in an all-round way in one breath.
Now that everyone has started to take out their deposits, the next step is to spend money on the stock market or the property market. I hope the market can give good enough products to catch the money.